Posts in Category: Finance
Battery Rebate’ The Day Your Power Goes Out Is When You’ll Find Out What Your Battery Actually Does
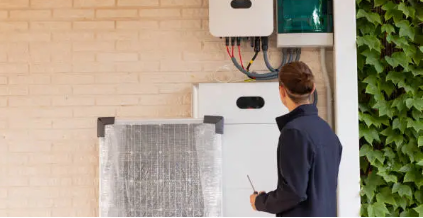
Sarah and Michael have done everything they thought they needed to prepare for rising electricity costs. Their rooftop solar system generates power during the day, they’ve installed a home battery after claiming a battery rebate, and they assumed they had been protected when the grid failed.
The Battery Has Energy—But That Doesn’t Mean Your House Can Use It
Sarah and Michael’s battery is working exactly as designed. It stores electricity generated by their solar panels and is ready to discharge when needed.
The problem is that their system wasn’t configured to automatically supply the home during a grid outage.
Under normal conditions, their solar and battery system operates alongside the electricity grid. When the grid goes down, the system may shut down or isolate itself to prevent electricity from being sent back into power lines while network crews are working.
This safety mechanism is essential, but it creates a surprising outcome for homeowners who assume stored energy automatically means uninterrupted electricity.
● Grid-connected operation isn’t the same as backup operation: A battery can reduce grid consumption without providing electricity during an outage.
● Blackout protection may require additional equipment: Some installations need specific backup hardware, switching equipment or an appropriate inverter configuration.
● The system must be designed for the job: If backup power wasn’t part of the original installation, the battery may not be able to power the home during an outage.
This is why homeowners considering a battery rebate should look beyond the advertised storage capacity. A battery’s ability to store energy and provide emergency power are separate questions.
In Adelaide, where severe weather can cause unexpected power interruptions, that distinction deserves serious attention before installation—not after the first blackout.
What Actually Keeps Running During an Outage?
Even when a battery system is configured for backup, homeowners shouldn’t assume every appliance in the house will continue operating normally.
Many backup systems are designed around essential loads. Instead of powering the entire property, the system supplies electricity to selected circuits considered important during an outage.
The difference becomes particularly important during an Adelaide summer blackout. Keeping a fridge and a few lights operating is one thing. Running a large ducted air conditioner for several hours requires a completely different amount of energy.
The battery may have plenty of capacity on paper, but the inverter must also handle the electrical load.
That’s why the right question isn’t simply, “How many kilowatt-hours does my battery store?”
It’s also, “Which appliances can it actually power when the grid is down?”
Your Battery’s Inverter and State of Charge Can Change the Outcome
Imagine the same storm hitting Adelaide two years later. Sarah and Michael have upgraded their system to include backup functionality.
This time, when the grid fails, selected lights stay on, and the refrigerator continues running. But their air conditioner still won’t start.
The reason could be a combination of inverter limitations, appliance demand and battery management.
The inverter plays a crucial role by converting the battery’s stored DC power into usable AC power for household appliances. Its power output determines how much electrical demand the backup system can handle at any given moment.
Meanwhile, the battery’s state of charge matters enormously.
● Battery capacity: The amount of energy a battery can store and use over time.
● Inverter capacity: Determines how much electrical power can be delivered at once.
● State of charge: Determines how much energy is actually available when the outage begins.
●
Consider a blackout that starts after several cloudy days. If the battery is only partially charged, the household may have significantly less backup duration than expected.
Alternatively, a fully charged battery might provide enough energy for essential appliances for many hours, but it can drain rapidly if several high-demand devices operate simultaneously.
This is where a battery rebate can complicate consumer expectations. An incentive may make battery ownership more accessible, but it doesn’t automatically mean the resulting system is optimised for emergency backup. The rebate is only one part of the decision; system design determines what happens when the grid disappears.
The Questions to Ask Before the Next Blackout
The most uncomfortable time to discover your battery isn’t configured for backup is during an actual outage.
Before installing or upgrading a system, Adelaide homeowners should ask their installer to explain exactly what will happen when the grid fails.
● Will the battery operate during a blackout? Confirm whether the system includes the necessary backup functionality and whether it automatically transitions to backup mode.
● Which circuits will remain powered? Request a clear list of essential circuits and appliances, rather than assuming the entire home will remain operational.
● How long will backup power last? Request realistic scenarios based on your household’s actual electricity consumption, battery capacity and likely state of charge.
It’s also worth asking what happens when the battery is nearly empty. Some systems can recharge from solar during an outage, but this depends on the system architecture, inverter configuration, available sunlight, and other technical factors.
The answers matter because backup power ultimately comes down to expectations.
A homeowner who expects to keep a refrigerator, medical equipment and internet connection running may have very different requirements from someone expecting to operate an entire home as if nothing happened.
Don’t Wait for the Storm to Test Your Battery
The fictional blackout that caught Sarah and Michael off guard could happen to any Adelaide household. The lesson isn’t that home batteries are unreliable. Homeowners need to understand exactly what they have purchased.
A battery can store solar energy and reduce grid dependence, but it offers little or no protection during a blackout if it isn’t designed and configured for backup operation.
So, if you’re considering a battery installation or planning to claim a battery rebate, don’t stop at questions about storage capacity, savings or incentives. Ask the more important question: “What exactly will happen in my home when the power goes out?”
Your next step should be to have a qualified installer assess your home’s energy needs and provide a clear backup power plan. Confirm the inverter’s capabilities, identify essential-load circuits, understand your expected battery runtime and establish whether solar recharging is possible during an outage.
Business Insurance Broker in Adelaide: Why Partnering with a Qualified Business Insurance Broker in Adelaide, SA is Essential for Tailored Coverage and Risk Management
Running a business in Adelaide comes with its own unique opportunities and challenges. From navigating local regulations to managing industry-specific risks, every business requires a solid foundation of protection to thrive. It is where a qualified business insurance broker becomes an invaluable partner. Far beyond simply recommending a policy, these professionals provide tailored solutions that safeguard business owners from unexpected losses, ensure compliance, and allow them to focus on growth.
Understanding the Role of a Qualified Business Insurance Broker
A qualified business insurance broker is not just a middleman between insurers and business owners. They act as trusted advisors who evaluate your company’s unique risk profile, identify vulnerabilities, and design insurance strategies that align with your goals. Unlike general insurance agents tied to a single provider, brokers have access to a vast network of insurers. This independence allows them to compare multiple options and negotiate the most comprehensive coverage at competitive rates.
Their expertise also extends to claims support, helping business owners navigate the often complex and time-consuming process of lodging and settling claims. In short, a broker doesn’t just secure coverage—they actively manage risks throughout the lifecycle of a business.
Why Adelaide Businesses Need Tailored Insurance Solutions
Adelaide’s business environment is diverse, encompassing a range of industries, including wine production, healthcare, construction, and professional services. Each sector faces distinct risks that require more than just a “one-size-fits-all” insurance policy. For instance:
Construction firms may face risks related to equipment damage, site liability, or worker safety.
Retail businesses: Might need protection against theft, property damage, and cyber incidents involving customer data.
Professional service providers may be exposed to liability for errors, omissions, or contractual disputes.
A qualified business insurance broker understands these nuances and customises policies to ensure no critical gap is left uncovered. This personalised approach reduces the likelihood of costly financial setbacks in the event of unexpected events.
Risk Management Beyond Insurance
While insurance is essential, risk management extends beyond purchasing policies. A qualified business insurance broker brings a strategic perspective by helping business owners anticipate potential issues and proactively mitigate them. It can include:
Conducting regular risk assessments to identify emerging threats.
Recommending safety protocols to minimise workplace accidents.
Advising on cybersecurity measures to protect sensitive information.
Ensuring compliance with industry-specific laws and government regulations.
This proactive partnership helps businesses reduce claims frequency, control premiums, and maintain long-term financial stability.
The Local Advantage: Why Choose a Broker in Adelaide
Working with a qualified business insurance broker based in Adelaide provides an additional advantage: local knowledge. Brokers who understand the South Australian business landscape can better identify region-specific risks, such as:
Environmental factors, such as bushfires and extreme weather events.
Industry regulations in South Australia are unique.
Local supply chain challenges that may affect manufacturing or retail businesses.
By combining their expertise with local insights, Adelaide-based brokers create strategies that are both practical and relevant to the community in which businesses operate.
Navigating Complex Insurance Markets
Insurance markets are constantly evolving. Premiums fluctuate due to economic conditions, new legislation may require additional coverage, and emerging risks, such as cybercrime, continue to grow. For a business owner focused on day-to-day operations, keeping track of these changes can be overwhelming.
A qualified business insurance broker stays informed about these developments, ensuring your coverage evolves as risks change. They monitor policy renewals, renegotiate terms when necessary, and keep you informed about new insurance products that may better suit your needs. This ongoing support is what distinguishes brokers from a simple online insurance purchase.
The Value of Professional Advocacy During Claims
One of the most stressful moments for any business owner is dealing with a claim. Whether it’s property damage, liability issues, or loss of income, the claims process can be lengthy and complex. A qualified business insurance broker acts as your advocate during this time, handling communication with insurers and ensuring your case is presented accurately and fairly.
Conclusion:
In Adelaide’s dynamic business landscape, protecting your company against risk is not optional—it’s essential. Partnering with a qualified business insurance broker offers more than access to policies; it provides tailored coverage, proactive risk management, local expertise, and professional advocacy during claims. By choosing the right broker, Adelaide businesses gain a strategic ally who ensures long-term security and resilience.
Non Bank Lenders: An Alternative Path to Financing
In New Zealand’s dynamic financial landscape, non-bank lenders have emerged as an excellent alternative to traditional banking institutions. These lenders offer a vast range of financial products and services, significantly catering to individuals and businesses that may not successfully fit the rigid criteria of conventional banks. This article delves into the world of non-bank lenders in New Zealand, exploring their offerings, benefits, and why they might be the right choice for your financial needs. For more information about the small business non bank lenders, click here.
 What Are Non-Bank Lenders?
Non-bank lenders are financial institutions that significantly provide loans and other credit services without holding a banking license. Unlike traditional banks, they do not accept deposits from the public. Instead, they source their funding through private investors, wholesale markets, or securitising loans. This unique structure allows non-bank lenders to operate with greater flexibility, offering tailored solutions to customers who mainstream banks may underserve.
Why Choose Non-Bank Lenders in New Zealand?
There are several compelling reasons why New Zealanders are increasingly turning to non-bank lenders for their financial needs:
- Flexibility in Lending Criteria: Non-bank lenders often have more relaxed lending criteria compared to traditional banks. This flexibility is remarkably beneficial for individuals with non-standard income streams, such as freelancers, contractors, or small business owners. If a bank has turned you down due to a lack of credit history or irregular income, a non-bank lender might be able to assist you.
- Competitive Interest Rates: While interest rates vary depending on the lender and the borrower’s financial situation, non-bank lenders can offer competitive rates, especially for short-term loans or specialised financial products. Some non-bank lenders also provide fixed-rate options, offering predictability in repayments.
- Personalised Service: Non-bank lenders in New Zealand often pride themselves on offering more personalised customer service. They take the time to understand the unique needs of each borrower, providing tailored solutions rather than a one-size-fits-all approach. This level of service can be particularly appealing to those seeking a more human touch in their financial dealings.
- Quick and Efficient Processes: The application and approval processes with non-bank lenders are generally faster and more streamlined compared to traditional banks. With less bureaucracy and fewer layers of approval, borrowers can often access funds more quickly, making non-bank lenders an attractive option for urgent financial needs.
Types of Loans Offered by Non-Bank Lenders in New Zealand
Non-bank lenders offer a wide array of financial products, catering to various needs:
- Personal Loans: Whether you need to consolidate debt, cover medical expenses, or finance a significant purchase, non-bank lenders offer personal loans with flexible terms. These loans can be significantly secured or unsecured, depending on the lender and the borrower’s credit profile.
- Home Loans and Mortgages: For those looking to enter the property market or refinance an existing mortgage, non-bank lenders provide a range of home loan options. They are often more willing to consider applications from individuals with low deposits or complex financial situations, such as self-employed borrowers.
- Business Loans: Non-bank lenders support New Zealand’s entrepreneurial spirit by offering business loans tailored to the overall specific needs of small and medium-sized enterprises (SMEs). Whether it’s for expansion, inventory purchase, or working capital, these loans can provide the necessary financial boost without the stringent requirements of traditional banks.
- Car Loans: If you’re in the market for a new vehicle, non-bank lenders offer car loans with competitive rates and flexible repayment options. They can also assist those with less-than-perfect credit, helping them get behind the wheel sooner.
- Bridging Loans: For borrowers needing short-term finance to bridge a gap, non-bank lenders offer bridging loans. These are typically used in property transactions but can be adapted for other scenarios where immediate cash flow is essential.
Conclusion:
Non-bank lenders in New Zealand provide a valuable alternative for those seeking flexible, personalised, and efficient financial solutions. Whether you’re an individual with unique income circumstances or a business needing quick access to capital, these lenders offer a range of products that might not be available through traditional banks.